

Vol. I, Ch. 10 · Part 3. Enterprise Architectures · Week 5
Enterprise Capital Architecture
Jump to any chapter
Volume I: Foundations and Mathematical Framework
- Ch. 1Introduction to Dynamic Corporate Transformation
- Ch. 2Enterprise Systems and Transformation
- Ch. 3Mathematical Foundations
- Ch. 4Enterprise Modeling Principles
- Ch. 5Enterprise State Representation
- Ch. 6Enterprise Transformation Operators
- Ch. 7Dynamic Enterprise Systems
- Ch. 8Stochastic Enterprise Dynamics
- Ch. 9Enterprise State Architecture
- Ch. 10Enterprise Capital Architecture
- Ch. 11Enterprise Performance Architecture
- Ch. 12Enterprise Risk, Resilience, and Robustness Architecture
- Ch. 13Unified Enterprise Transformation Architecture
- Ch. 14Mathematical Analysis of the Unified Enterprise Transformation Architecture
- Ch. 15Mathematical Formulation of Enterprise Optimization
- Ch. 16Synthesis, Future Directions, and Transition to Volume II
Volume II: Enterprise Optimization & Applications
- Ch. 1Introduction to Enterprise Optimization
- Ch. 2The General Enterprise Optimization Problem Revisited
- Ch. 3Convex Enterprise Optimization
- Ch. 4Nonlinear and Mixed-Integer Enterprise Optimization
- Ch. 5Dynamic Enterprise Optimization
- Ch. 6Optimal Control of Enterprise Systems
- Ch. 7Dynamic Programming for Enterprise Systems
- Ch. 8Hamilton–Jacobi–Bellman Enterprise Framework
- Ch. 9Stochastic Enterprise Optimization
- Ch. 10Neuro-Fuzzy Robust Enterprise Optimization
- Ch. 11Distributionally Robust Enterprise Optimization
- Ch. 12Multi-Objective Enterprise Optimization
- Ch. 13Machine Learning for Enterprise Transformation
- Ch. 14Artificial Intelligence for Enterprise Optimization
- Ch. 15Enterprise Digital Twins and Autonomous Enterprise Transformation
- Ch. 16Enterprise Applications and Integrated Transformation Case Studies
Lecture
Watch the chapter summary
Watch the chapter summary
Vol. I, Ch. 10Enterprise Capital Architecture
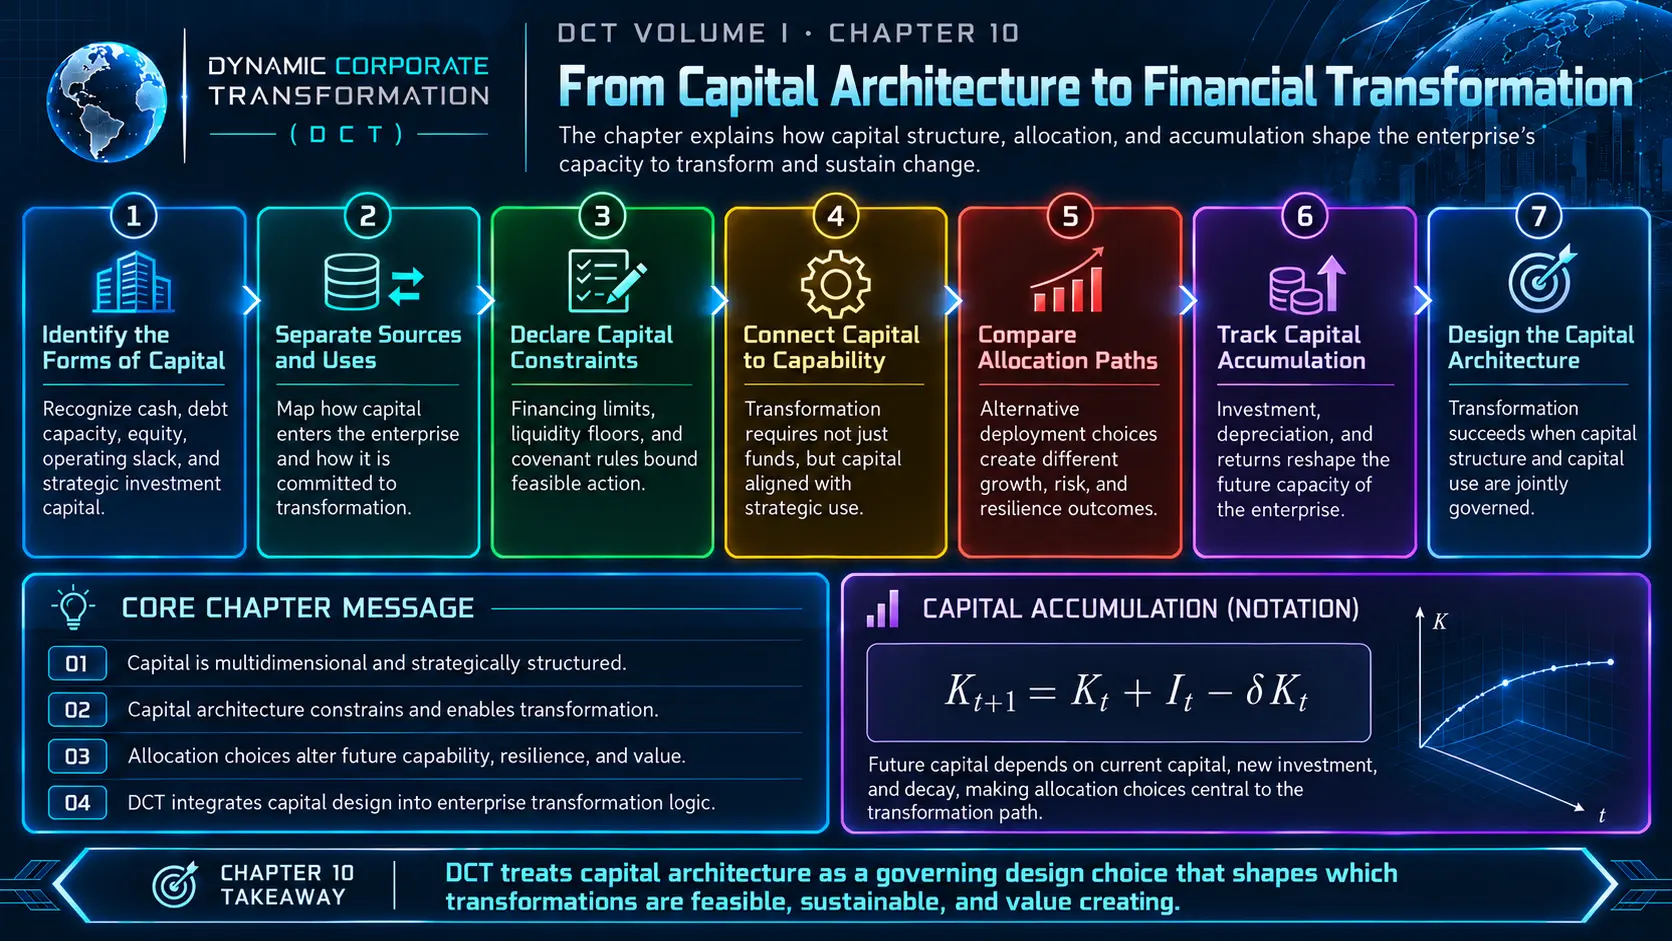
Learning outcomes
After completing this chapter, the reader should be able to:
- Explain why a company's capacity depends on more than its financial capital, and describe the forms of enterprise capital by how they behave: how fast they decay, how long they take to build, and whether they can be bought or separated from the people who carry them.
- Account for any capital stock as investment, use, decay, and conversion, recognize the loss in converting one form into another, and use the unexplained residual to detect channels the ledger has missed.
- Use the accumulation law to price the rent on a capital stock and the minimum time to build it, and explain why capital is fast to destroy and slow to rebuild.
- Distinguish the bottleneck and complementarity regimes of capital interaction, and explain what each implies for where the next dollar should go.
- Allocate a capital budget across forms by equalizing marginal returns, recognize when zero funding is optimal, and audit a capital architecture for consistency.
Reading guide
Work through the chapter in section order; the full development, proofs, and worked examples are in the book — this page indexes them and does not replace them.
10.1 Why Capital Is More Than Money
10.2 Capital Beyond Finance
Proposition 10.1 (Enterprise Value Depends on Multidimensional Capital)10.3 The Enterprise Capital Architecture
Definition 10.1 (Enterprise Capital) · Definition 10.2 (Enterprise Capital Architecture) · Theorem 10.1 (Enterprise Capital Representation Theorem)10.4 The Forms of Enterprise Capital
Definition 10.3 (Financial Capital) · Definition 10.4 (Human Capital) · Definition 10.5 (Intellectual Capital) · Definition 10.6 (Technological Capital) · Definition 10.7 (Organizational Capital) · Definition 10.8 (Relational Capital) · Definition 10.9 (Strategic Capital) · Table 10.1 · Table 10.2 · Table 10.310.5 Capital Dependencies
Definition 10.10 (Capital Dependency) · Proposition 10.2 (Capital Components Are Mutually Interdependent) · Theorem 10.2 (Capital Dependency Theorem)10.6 Capital Accumulation and Depletion
Definition 10.11 (Capital Accumulation) · Definition 10.12 (Capital Depletion) · Theorem 10.3 (Capital Accumulation Theorem) · Proposition 10.3 (Accumulation Increases Transformation Capacity) · Proposition 10.4 (Depletion Reduces Adaptability, Asymmetrically) · Figure 10.110.7 Capital Allocation and Productivity
Theorem 10.4 (Capital Productivity Theorem) · Figure 10.210.8 Architecture Consistency and Capital Dynamics
Proposition 10.5 (Transformation Modifies the Capital Architecture) · Theorem 10.5 (Enterprise Capital Architecture Consistency Theorem) · Table 10.4Worked Example 10.1: Keep the Engineers or Rebuild Them?
Table 10.5 · Figure 10.3AXIOM Lab 1.10: Meridian's Capital Ledger
Appendix 10.A: Formal Statements and Proofs
Theorem 10.2, formal statement and proof · Theorem 10.3, formal statement and proof · Theorem 10.4, formal statement and proof
Concepts in this chapter
AXIOM Lab
AXIOM Lab 1.10: Meridian's Capital Ledger
The business situation. Meridian's chief financial officer wants a capital view of the transformation: which non-financial stocks each of the three options builds or consumes, what each stock costs to hold, and how fast each can be rebuilt. The transformation office must also defend its training and platform budgets against a proposal to cut them for a year. You support the chief financial officer.
Your objective. Use AXIOM to build Meridian's capital vector, price the rent and the rebuild time of its key stocks, test allocation policies, and audit the capital ledger for channels it has missed.
What you will do. Open AXIOM, choose Lab 1.10 (module AXIOM-10), and load the Meridian capital model.
- Build the capital vector. In the capital vector builder, declare financial, human, technological, and organizational capital with carriers, units, indicators, and error bars (Table 10.3).
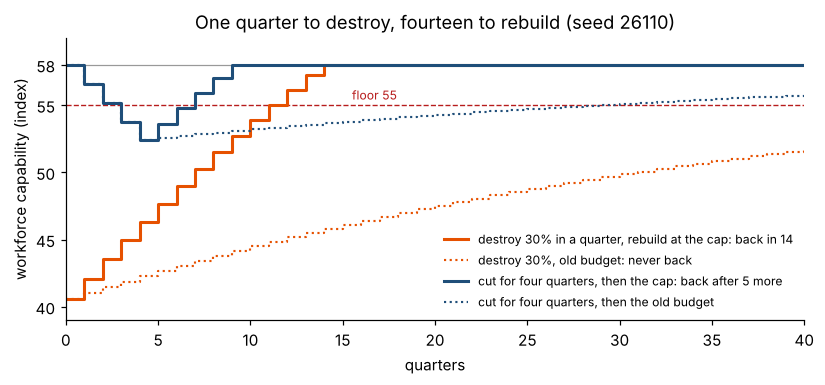
- Price the rent. In the accumulation simulator, hold each stock at its target with its sustaining flow; then cut investment for four quarters and watch the decline, and the recovery at the old budget and at the cap.
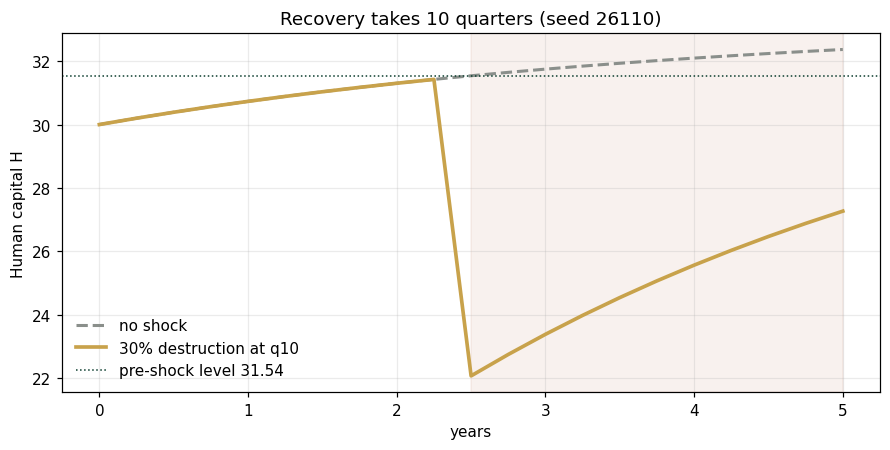
- Test the asymmetry. Destroy 30 percent of human capital in one quarter and count the quarters needed to recover.
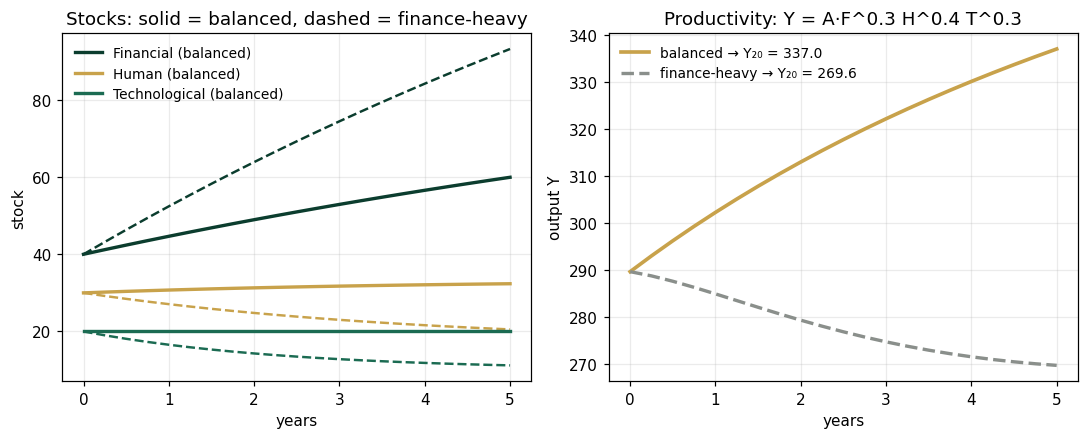
- Allocate a budget. On the allocation bench, split a budget across forms—balanced, finance-heavy, bottleneck first—compare the capacity each buys, and read the shadow value .
- Audit the ledger. Run the plug auditor on a capital record with one undeclared conversion channel, and locate the channel from the sign and timing of the residual.
What to look for. Holding a stock costs its rent for as long as it is wanted (Theorem 10.3(ii)); after a cut, the stock recovers only slowly at the old budget and, at the cap, no faster than the time to build (Theorem 10.3(iii)); and spending off the bottleneck buys nothing (Theorem 10.2(i)).
Discussion questions. (1) Which of Meridian's stocks is being held at less than its rent, and what will that cost later? (2) Which of the three options consumes the slowest stocks, and what is its repurchase liability? (3) What would you publish beside the capital budget so that the committee can see the bottleneck?
Deliverable. A one-page capital memo to the chief financial officer: the capital vector with error bars, the rent on each stock, the time to rebuild what each option consumes, the bottleneck, and one reallocation you would propose.
Time and outcomes. About 75 minutes; supports LOS 10.2, 10.3, 10.4, and 10.5. The Chapter 10 Excel workbook and Python notebook on this page reproduce the lab's calculations.
This chapter is instrumented by:
Launch the module, load the chapter model, modify inputs, run the optimization, and compare against the worked examples in the book.
Downloads
All three companions come from the chapter's seeded engine: the notebook and workbook reproduce the book's Worked Example and AXIOM Lab and check every number against it — the MFMF convention, carried forward.