

Vol. I, Ch. 8 · Part 2. Mathematical Representation · Week 4
Stochastic Enterprise Dynamics
Jump to any chapter
Volume I: Foundations and Mathematical Framework
- Ch. 1Introduction to Dynamic Corporate Transformation
- Ch. 2Enterprise Systems and Transformation
- Ch. 3Mathematical Foundations
- Ch. 4Enterprise Modeling Principles
- Ch. 5Enterprise State Representation
- Ch. 6Enterprise Transformation Operators
- Ch. 7Dynamic Enterprise Systems
- Ch. 8Stochastic Enterprise Dynamics
- Ch. 9Enterprise State Architecture
- Ch. 10Enterprise Capital Architecture
- Ch. 11Enterprise Performance Architecture
- Ch. 12Enterprise Risk, Resilience, and Robustness Architecture
- Ch. 13Unified Enterprise Transformation Architecture
- Ch. 14Mathematical Analysis of the Unified Enterprise Transformation Architecture
- Ch. 15Mathematical Formulation of Enterprise Optimization
- Ch. 16Synthesis, Future Directions, and Transition to Volume II
Volume II: Enterprise Optimization & Applications
- Ch. 1Introduction to Enterprise Optimization
- Ch. 2The General Enterprise Optimization Problem Revisited
- Ch. 3Convex Enterprise Optimization
- Ch. 4Nonlinear and Mixed-Integer Enterprise Optimization
- Ch. 5Dynamic Enterprise Optimization
- Ch. 6Optimal Control of Enterprise Systems
- Ch. 7Dynamic Programming for Enterprise Systems
- Ch. 8Hamilton–Jacobi–Bellman Enterprise Framework
- Ch. 9Stochastic Enterprise Optimization
- Ch. 10Neuro-Fuzzy Robust Enterprise Optimization
- Ch. 11Distributionally Robust Enterprise Optimization
- Ch. 12Multi-Objective Enterprise Optimization
- Ch. 13Machine Learning for Enterprise Transformation
- Ch. 14Artificial Intelligence for Enterprise Optimization
- Ch. 15Enterprise Digital Twins and Autonomous Enterprise Transformation
- Ch. 16Enterprise Applications and Integrated Transformation Case Studies
Lecture
Watch the chapter summary
Watch the chapter summary
Vol. I, Ch. 8Stochastic Enterprise Dynamics
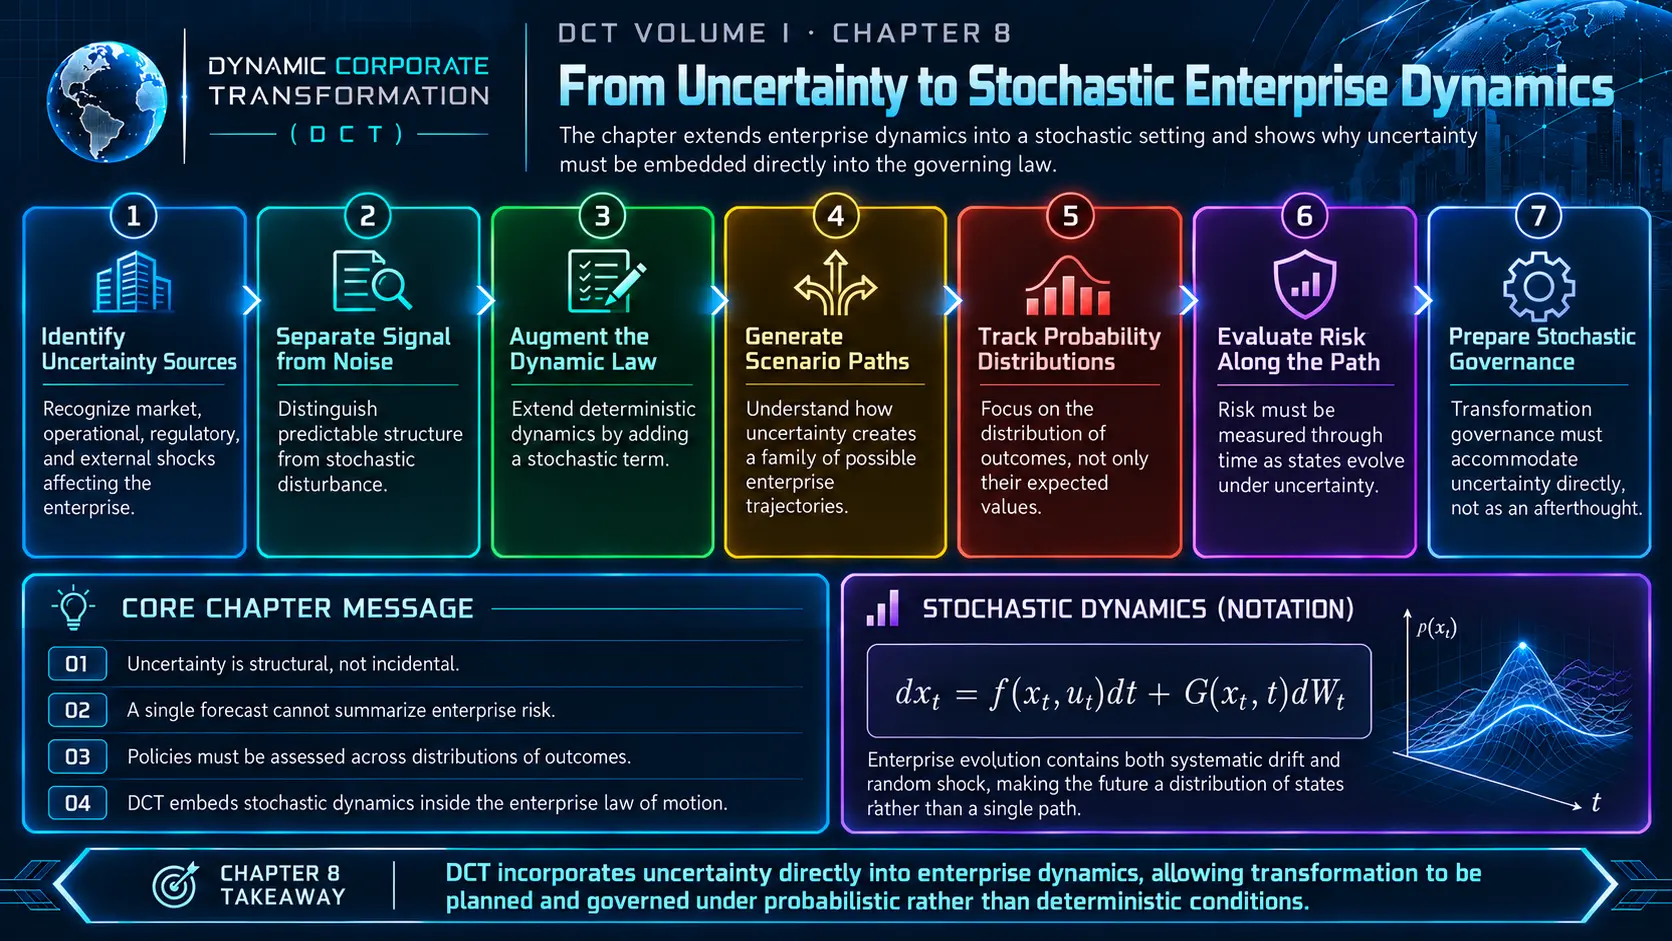
Learning outcomes
After completing this chapter, the reader should be able to:
- Explain why a transformation plan needs probability: where uncertainty enters a company model, and why the honest forecast is a distribution of outcomes rather than a single path.
- Describe how the distribution of a company's state evolves—the fan chart as the forecast—and test whether multi-year risk views are consistent with one another.
- Distinguish the steady accumulation of small shocks from discrete events, and use each to size a company's volatility budget and the plan and risk lines of an event exposure.
- Explain when a deterministic plan is the correct average and when curvature biases it (the flaw of averages), and how programs amplify or damp the uncertainty they inherit.
- Estimate risks such as a liquidity breach by Monte Carlo simulation, and report each estimate with an honest error bar.
Reading guide
Work through the chapter in section order; the full development, proofs, and worked examples are in the book — this page indexes them and does not replace them.
8.1 Why Transformation Needs Probability
8.2 Sources of Enterprise Uncertainty
Definition 8.1 (Enterprise Uncertainty) · Proposition 8.1 (Enterprise Evolution Is Inherently Stochastic) · Table 8.18.3 Probability Foundations for Enterprise Analysis
Lemma 8.1 (Independence Lemma) · Definition 8.2 (Enterprise Stochastic Process) · Definition 8.3 (Enterprise Noise) · Definition 8.4 (Enterprise Probability Distribution) · Table 8.2 · Table 8.38.4 Stochastic Enterprise Systems in Discrete Time
Definition 8.5 (Stochastic Enterprise Trajectory) · Theorem 8.1 (Existence of Stochastic Enterprise Trajectories) · Proposition 8.2 (Trajectories Possess Distributions) · Proposition 8.3 (Deterministic Dynamics Are the Degenerate Case)8.5 The Evolution of Enterprise State Distributions
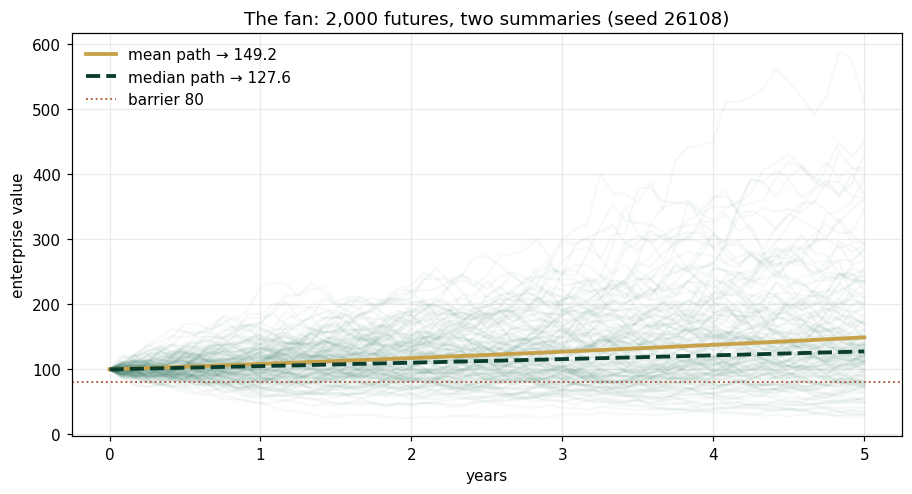
Definition 8.6 (Enterprise Transition Probability) · Definition 8.7 (Enterprise Expected State) · Definition 8.8 (Enterprise Variance) · Theorem 8.2 (Enterprise State Distribution Theorem) · Proposition 8.4 (Distributions Evolve Continuously) · Figure 8.18.6 Enterprise Diffusion
Definition 8.9 (Enterprise Diffusion) · Theorem 8.3 (Diffusion Representation Theorem) · Figure 8.28.7 Enterprise Jump Processes and Jump-Diffusion
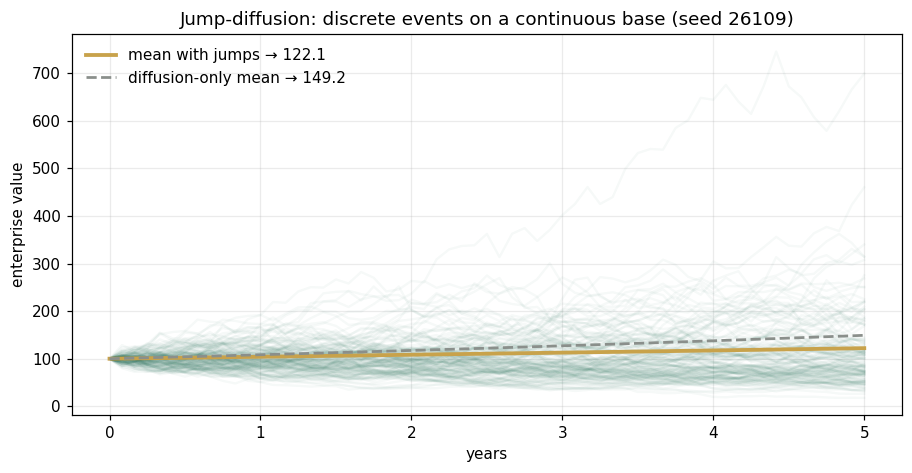
Definition 8.10 (Enterprise Jump Process) · Theorem 8.4 (Jump-Diffusion Enterprise Dynamics Theorem) · Figure 8.38.8 Expected Evolution and the Flaw of Averages
Theorem 8.5 (Expected Enterprise Evolution Theorem) · Proposition 8.5 (Uncertainty Propagates Through Transformation Operators)8.9 Monte Carlo Simulation of Enterprise Dynamics
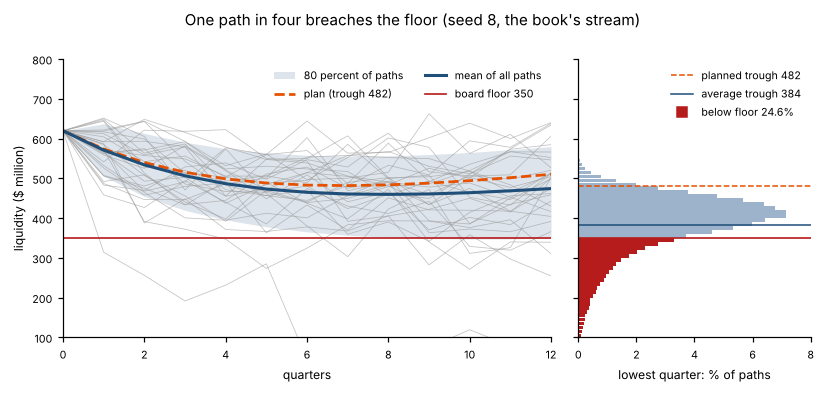
Table 8.4Worked Example 8.1: Will the Digital Program Breach the Floor?
Table 8.5 · Figure 8.4AXIOM Lab 1.8: Putting Odds on Meridian's Plan
Appendix 8.A: Formal Statements and Proofs
Theorem 8.2, formal statement and proof · Theorem 8.3, formal statement and proof · Theorem 8.4, formal statement and proof · Theorem 8.5, formal statement and proof
Concepts in this chapter
AXIOM Lab
AXIOM Lab 1.8: Putting Odds on Meridian's Plan
The business situation. Meridian's board has asked for a risk view of the digital program that it can trust: the probability of breaching the liquidity floor, what drives it, and what each mitigation buys. The chief risk officer also wants the planning pack's multi-year fans and event provisions checked for consistency. You support the chief financial officer.
Your objective. Use AXIOM to see how fans form and settle, price the company's event risks, measure the flaw of averages, and put an honest probability on the floor breach under each mitigation.
What you will do. Open AXIOM, choose Lab 1.8 (module AXIOM-08), and load the Meridian stochastic model.
- Watch the fan form. In the distribution evolver, start Industrial Systems' revenue deviation after a strong quarter and watch its distribution drift and widen; then sweep the persistence through one in the variance saturator and watch the band stop settling.
- Check the multi-year view. Enter a one-year and a three-year fan from the planning pack in the Chapman–Kolmogorov checker and test whether they compose.
- Price an event risk. In the jump lab, generate regulatory interventions at 0.15 a year, read the plan line and the risk line, then condition on five quiet years and compare next year's chance.
- Feel the flaw of averages. In the convexity demonstration, bend a cost function and watch the gap between the average cost and the cost at average volume.
- Put odds on the program. On the Monte Carlo bench, reproduce Worked Example 8.1: vary the number of paths and watch the error bar shrink, switch each channel off in turn, and test the standby line and the phased build.
What to look for. A stable company's fan stops widening, while an accumulator's never does (Theorem 8.3); quiet years do not make an event “due” (Theorem 8.4); and the average trough lies well below the planned trough (Theorem 8.5).
Discussion questions. (1) Which of Meridian's plan numbers would you restate as probabilities, and with what error bars? (2) How would you explain to the board that the plan's trough and the average trough differ by almost $100 million? (3) Which lever would you fund first, and why?
Deliverable. A one-page risk memo to the board stating the breach probability with its error bar, the share due to each channel, the effect of each lever, and a recommendation against the 5 percent appetite.
Time and outcomes. About 60 minutes; supports LOS 8.2, 8.3, and 8.5. The Chapter 8 Excel workbook and Python notebook on this page reproduce the lab's calculations.
This chapter is instrumented by:
Launch the module, load the chapter model, modify inputs, run the optimization, and compare against the worked examples in the book.
Downloads
All three companions come from the chapter's seeded engine: the notebook and workbook reproduce the book's Worked Example and AXIOM Lab and check every number against it — the MFMF convention, carried forward.